

Quick answer: The ADHD tax is the extra money you lose to executive dysfunction rather than to bad math: late fees, forgotten subscriptions, replacing things you already own, food that rots. Card issuers in the CFPB’s December 2025 market report charged $17.0 billion in late fees in 2024, and the $8 cap that was supposed to replace large issuers’ typical $32 fee (the CFPB’s 2022 figure) was blocked in court. Autopay and a statement audit are a practical place to start.
You paid the bill. The money was sitting right there in checking. You just… didn’t click the button on the day the button needed clicking, and now there’s a $32 line item on your statement that bought you absolutely nothing.
That’s the ADHD tax. Not a real tax, obviously. It’s a nickname for the money that leaks out of your life when deadlines, follow-through, and “future you” are harder to manage. And the thing that makes it sting isn’t the number. It’s that it feels like a fine for being yourself.
Here’s the good news: much of the fix for the ADHD tax is mechanical. You don’t need more discipline. You need fewer moments where remembering is required.
Key takeaways
- The ADHD tax is a real pattern, but the viral “$15,000 a year” figure isn’t a count of fees and waste. Research estimates in that range, like $8,900 to $15,400 a year in a 2006 study, measure lost income.
- Two rules that would have made it cheaper got struck down in 2025, so late fees like the $32 average the CFPB measured in 2022 are still allowed, and subscriptions fall under older federal rules instead of the new click-to-cancel rule.
- A quick bank statement audit tells you your actual number, instead of an internet estimate.
- The approach this guide recommends isn’t willpower. It’s automation plus one screen you can glance at without doing math.
What the ADHD tax actually is
Strip away the memes and it’s four repeating categories: penalties (late fees, overdrafts, parking tickets, library fines), zombie spending (subscriptions you meant to cancel months ago), duplicates (the extra pair of scissors, the spare charging cable, the sunscreen you already own), and decay (produce that liquefies, a gym membership you barely used, the return window that closed while the box sat by the door).
Those usually aren’t choices you meant to make. That’s a big part of what separates the ADHD tax from ordinary overspending. You didn’t want the thing. You wanted the thing you already bought, and then time did what time does.
The research backs the pattern up, carefully. A community study of 1,292 adults published in PLOS One found that participants in its ADHD and Adult-only ADHD groups, which were based on self-reported symptoms, reported significantly more impulsive buying, used avoidant and spontaneous decision styles more often, and saved money less often than the No ADHD group. The honest caveat, straight from the same paper: once the researchers controlled for personality, depression, and demographics, impulsive buying and decision styles were no longer significantly linked to ADHD symptoms. Translation: the pattern is real, the causal story is messier than a headline, and you are not uniquely broken.
Why the ADHD tax didn’t get cheaper
This part matters, because it changes the math.
In March 2024 the CFPB finalized a rule capping credit card late fees at $8 for larger issuers, those with more than 1 million open accounts, down from a typical $32. Those issuers could still charge more if they proved a higher fee covered their collection costs. Its own analysis said late fees cost American families more than $14 billion in 2022, and that the cap would save the more than 45 million people who are charged late fees an average of $220 a year. By 2024, the issuers in the CFPB’s December 2025 credit card market report were charging $17.0 billion in late fees, up 17 percent since 2022. The average fee at big issuers had crept from $23 at the end of 2010 to $32 in 2022.
That cap got blocked. A federal court vacated it in April 2025, and the CFPB’s own rule page still lists it as stayed. So big issuers can keep charging fees like the $32 average the CFPB measured in 2022.
Then in July 2025 the Eighth Circuit threw out the FTC’s “click to cancel” rule, the one that would have forced companies to let you cancel a subscription as easily as you signed up. The FTC started over with an advance notice of proposed rulemaking in March 2026, and the comment period closed April 13, 2026. That notice is a request for input, not a new rule, so it doesn’t change anything in your account settings yet.
Put those together: late fees and hard-to-cancel subscriptions, two common ways for a missed task to turn into a charge, both lost a new protection that was on the way. Nothing about this is your fault. It does, however, mean the defense has to come from your side of the table.
Do the math on your own ADHD tax
Skip the scary internet estimates. Open the last three months of statements and hunt for these six things. Three months, then multiply by four. That’s your annual number.
| What to search for | Typical hit | Your 3 months |
|---|---|---|
| “Late fee”, “past due” | $32 each (CFPB average, 2022) | ____ |
| “Overdraft”, “NSF” | $32–$35 each (CFPB medians, 2022–23) | ____ |
| Subscriptions you can’t picture using | check each monthly charge | ____ |
| Same item bought twice | look for repeats | ____ |
| Rush shipping / same-day delivery fees | add up the fees | ____ |
| Interest you’d have avoided by paying on time | varies | ____ |
Whatever your number turns out to be, it’s one you can work with, because leaks you can see can be plugged with some setup, not a personality transplant.
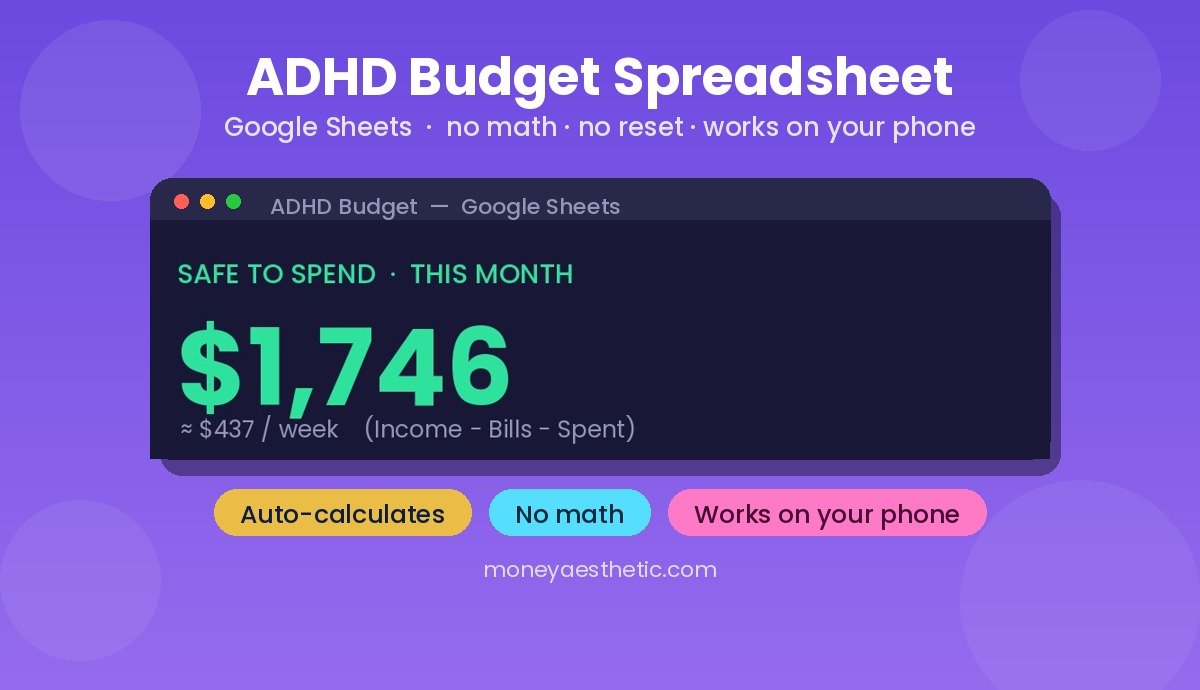
The catch: an audit is more useful when you can see the pattern month after month, and in a budgeting app with a deep category tree, fees like these can be easy to lose track of. That’s why the ADHD budget spreadsheet exists: one screen, a live “safe to spend” number, and a leaks section on that same screen instead of one buried in a category tree. No formulas to build, and no long setup to abandon halfway through.
Built for a brain that hates budgeting
One screen. One number that tells you what’s actually safe to spend this month. Income, bills, and leaks already wired up, with nothing to calculate. Log what you spend and let it do the math. $7.99.
Get the ADHD Budget Spreadsheet →Five leaks you can plug this week
- Autopay the minimum on each card, today. Not the full balance, just the minimum. As long as the payment clears, it keeps a late fee from being triggered. That one move covers a fee that can come back month after month.
- Do a card-level subscription sweep. Search your statement for anything charging the same amount monthly. Cancel by phone if the website makes you dig. The FTC’s click-to-cancel rule was struck down, but a federal law (ROSCA) still requires online subscription sellers to give you a simple way to stop recurring charges.
- Give returns a physical launchpad. One basket by the door, one recurring Sunday alarm. Return windows close quietly, and a missed one means keeping something you meant to send back.
- Buy the duplicate on purpose. Scissors in more than one room, a charger wherever you use one. Sounds wasteful. It can cost less than rebuying the “missing” one.
- Check one number, not a whole dashboard. Whatever you use, it should answer “can I spend this?” at a glance, or it gets easy to stop opening it. This is where a plain budget spreadsheet can beat a beautiful app you have to interpret.
If step five is where your systems usually die, that’s not a character flaw. It’s a design flaw, and a simpler template can help with it.
What people get wrong about the ADHD tax
“It’s 15,000 to 20,000 dollars a year.” You’ll see this a lot online. No study we found adds up late fees and wasted purchases to that total. Numbers that size show up in research on lost income, like a 2006 MedGenMed study that estimated $8,900 to $15,400 a year in lost income per person with ADHD in 2003. That’s a different cost. Your real figure comes from your statements.
“It means you’re bad with money.” The PLOS One study looked at decision style and impulsive buying. It didn’t measure math ability. A decision style isn’t the same thing as being bad at math.
“A better app will fix it.” Apps add steps: open, log in, wait, interpret. Each step is somewhere to fall off. Fewer decisions can matter more than more features.
“You should be able to get it to zero.” No. Which brings me to the thing I actually believe.
The unpopular fix: give the ADHD tax its own budget line
The usual instinct is to try to eliminate it. I think that’s why so many people bounce off budgeting entirely. You build a plan that assumes a version of you who doesn’t forget, then that version doesn’t show up, and the whole plan feels like a failure.
So do the opposite. Take your audited number, divide by twelve, and put it in your budget as a real category. Call it whatever you want. Whatever the amount, it’s forgiven in advance.
Two things happen. The occasional fee stops blowing a hole in your month, because it was already funded. And seeing the line each month shows you which leaks to plug next, without any white-knuckling. It’s the same logic as a sinking fund, just pointed at your executive function instead of your car tires.
You’re not paying a fine for having ADHD anymore. You’re paying a subscription to being a human being, at a price you set, and you can see exactly where it goes.
If you want the deeper system behind this, the full walkthrough lives in how to budget with ADHD, and if impulse purchases are the bigger leak for you, start with how to stop impulse buying instead. Either way, the goal is the same: a month that ends with money still in the account, and no mystery about where it went. There is an ADHD-specific version of that now too: how to stop spending money with ADHD.
ADHD tax FAQ
What is the ADHD tax?
The ADHD tax is the extra money people with ADHD lose to executive dysfunction rather than to overspending: late fees, forgotten subscriptions, duplicate purchases, expired returns, and wasted food. It’s a nickname, not an official term, and it describes a timing and follow-through problem rather than a spending problem.
How much does the ADHD tax cost per year?
No study we found adds up fees and wasted purchases into a yearly average. The $15,000 figure that circulates online sits near the top of a 2006 MedGenMed estimate of lost income ($8,900 to $15,400 a year per person with ADHD), which is a different cost. A practical way to find yours is a three-month statement audit. For scale, the CFPB estimated its $8 late-fee cap, which was later blocked in court, would have saved the more than 45 million people charged late fees an average of $220 a year.
Is the ADHD tax a real, documented thing?
The underlying pattern is documented. A PLOS One study of 1,292 adults found that participants in its ADHD and Adult-only ADHD groups, based on self-reported symptoms, reported significantly more impulsive buying and less frequent saving than the No ADHD group, though impulsive buying and decision styles were no longer significantly linked to ADHD symptoms once personality, depression, and demographics were controlled for. The big dollar amounts quoted online match a different kind of research: a 2006 MedGenMed study estimated $8,900 to $15,400 a year in lost income per person with ADHD, which isn’t the same as fees and waste.
What’s the fastest way to reduce the ADHD tax?
Turn on autopay for the minimum payment on each credit card today. It stops a fee that can come back month after month: credit card late fees, which averaged $32 at major issuers in 2022. Once it’s set, you don’t have to remember the due date, as long as the payment clears.
Why can card issuers still charge late fees like the CFPB’s 2022 average of $32 if there was a rule capping them at $8?
The CFPB’s $8 cap for larger issuers was finalized in March 2024, but it got caught up in litigation. A federal court vacated it in April 2025 and the CFPB’s rule page lists it as stayed, so major issuers can still charge their previous amounts, like the $32 average the CFPB measured in 2022.
Does ADHD medication reduce the ADHD tax?
Medication decisions belong with your prescriber, and this guide can’t tell you how treatment will affect your spending. Autopay and reminders run the same way whether or not you’re medicated, which is why they’re a practical first move.
Should I budget for the ADHD tax instead of trying to eliminate it?
That’s the approach this guide recommends. Take your audited annual figure, divide by twelve, and fund it as a monthly category. A funded fee doesn’t wreck the month, and seeing the line each month shows you which leaks to plug next.
What should an ADHD-friendly budget look like?
Look for one that shows what you can spend right now, on one screen, with no calculation. Deep category trees, multi-step apps, and daily manual entry add steps where it’s easy to fall off, which is why this guide suggests a one-screen spreadsheet with a live safe-to-spend number.

Grab the free monthly template
If the hard part is just seeing everything in one place, start there. The free Monthly Budget Template lays out your month on one sheet and does the adding for you, with no subscription to cancel.
Get the free Monthly Budget Template →This article is for general information only and isn’t financial, medical, or legal advice. Figures cited are from the sources linked above and may change. For decisions about your own money or ADHD treatment, talk to a qualified professional.